

Quicken Simplifi: Budget Smart
Quicken Inc.
- 4.3
- 1.27K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
Quicken Simplifi: Budget Smart Pros and Cons
Pros
- User-friendly interface for easy navigation.
- Real-time transaction updates enhance accuracy.
- Customizable budget categories for personalization.
- Automatic syncing with multiple accounts.
- Insightful financial reports simplify tracking.
Cons
- Subscription required after the trial period.
- Limited features in the free version.
- Occasional syncing issues with some banks.
- No offline mode for data access.
- Some advanced tools lack detailed customization.
 Analysis by All-app
When a household tries to keep track of shared costs, the hard part is often not doing the arithmetic; it is agreeing on which picture of the money to trust. I find Quicken Simplifi: Budget Smart most useful as a place to review personal finances and spending patterns, rather than as a substitute for a conversation between partners or housemates. That distinction matters: a clear view can make a budget easier to discuss, but it does not decide who is responsible for a bill or how expenses should be split.
A shared household picture, with individual boundaries
Imagine two people planning groceries, utilities, and a weekend outing while each still has personal purchases to manage. A spending plan and transaction history can help them look at the same household pressures and spot when routine costs are crowding out something they care about. I would use that view to prepare for a short check-in: what is due soon, what has changed, and what needs attention before the next payday.
The useful trade-off is that shared visibility does not automatically mean shared control. Before linking financial information, decide whose accounts are being connected and what each person is comfortable reviewing. If one person prefers to keep an account private, a household can still discuss a planned contribution or a general budget without treating full account access as a requirement. I would not connect an account simply to make a joint budget feel more complete.
Set it up around the way you actually manage money
Quicken Inc. makes this finance app, and its broad appeal is easy to understand: it is free to install, has an average rating of 4.3 from around 4,200 ratings, and has been installed over 500,000 times. It is rated for Everyone, though a finance tool is most useful when the person using it can understand the information and make sensible decisions about account access. In-app purchases range from around $8.99 to $95.90 per item, so I would check the current purchase details before committing to anything beyond the free download.
For a household, setup is a good moment to decide what the app should help you answer. If your main question is “How much room do we have after bills?”, make that the focus instead of trying to categorize every old transaction perfectly on day one. If your goal is to keep personal and shared spending distinct, take care when choosing which accounts to connect and how custom categories reflect your arrangement. A tidy setup is helpful only if it matches the boundaries everyone has agreed to.
I would also treat connected account information as a working view, not an unquestionable household ledger. If a transaction looks unfamiliar or a balance does not match what you expect, check the original account before changing a shared plan around it. This small pause is especially useful when several people are relying on the same budget conversation: it avoids turning a delayed or unclear entry into an argument about who spent what.
Turn money tracking into coordination
A practical routine can be simple: review upcoming bills, look at the spending plan, and then talk through any category that needs a decision. The app can help bring those topics into view; the people involved still need to agree on priorities, contributions, and timing. I like that distinction because it keeps a budgeting tool from becoming an awkward referee between partners or roommates.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Custom categories can make that conversation more concrete. A household might separate a shared grocery budget from individual meals out, or distinguish routine bills from occasional home costs. The benefit is not merely a prettier report: it is that people can discuss a category that means something to them instead of arguing over a broad label. My tip is to start with only the distinctions that affect decisions. Too many finely divided categories can turn upkeep into a chore, and a category system that nobody uses consistently will not clarify much.
There is also a small but useful workflow in attaching notes or receipts to transactions. For a purchase that needs explaining later, a note can preserve context while it is fresh, such as whether a household item was shared or personal. That can save a future round of guesswork. I would use this selectively rather than trying to document every routine purchase; the point is to make unusual or important transactions easier to understand, not to create paperwork for its own sake.
Age, trust, and who should use it
The Everyone age rating makes the app broadly accessible from a store-rating perspective, but that does not mean every child should manage family finances. I would keep account decisions and sensitive money discussions with the adults responsible for them. Older teens learning to budget may benefit from seeing how categories and spending plans work, but access should depend on the family’s comfort with the accounts and information involved—not on the rating alone.
For couples or housemates, trust is practical as well as personal. Talk first about what the app is for: a shared view of bills, a personal budget, or both. If one person expects complete transparency and another expects privacy, connecting accounts before resolving that difference can make the tool feel intrusive. I would agree on the purpose and boundaries first, then choose a setup that supports that agreement.
The app is a stronger fit for people who want an ongoing view of spending and upcoming obligations than for someone who only needs to split a single dinner bill. It may also be a poor match for anyone who would rather avoid linking accounts or who prefers to build every budget manually in a spreadsheet. Those approaches can offer more direct control, even if they ask the user to do more upkeep.
Getting Started with Quicken Simplifi
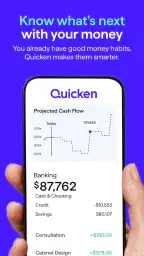
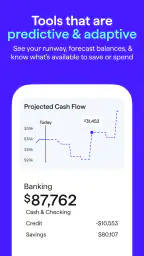
Diving into Quicken Simplifi is a breeze. The setup process is straightforward, and right off the bat, the app greets you with a clean interface that's easy on the eyes. Once you link your bank accounts, credit cards, and other financial data, Simplifi does its magic by providing you with a clear view of your financial landscape. No more guessing where your money went!
Features That Stand Out
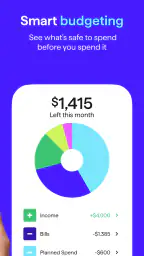
One of the most impressive features is the personalized spending plan. Simplifi doesn't just show you where your money is going; it helps craft a realistic budget based on your spending habits. The app also sends reminders for upcoming bills and alerts you when you're approaching your spending limits. It's like having a personal financial advisor in your pocket.
The tracking of subscriptions is another highlight. I didn't even realize how many subscriptions I had until Simplifi pointed them out. It helps you keep track of all those monthly payments and even suggests areas where you could save money. Talk about eye-opening!
User Experience
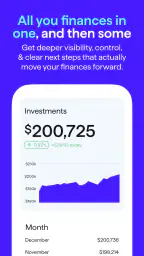
Using Simplifi feels intuitive. The app is designed to make financial management as painless as possible. With its sleek design and user-friendly navigation, even a finance novice can feel like a pro. The dashboard provides a snapshot of your financial health, and the reports feature gives detailed insights into your spending patterns.
One thing I love is the custom categories. You can tailor categories to fit your lifestyle, making the app more personalized. Plus, the ability to attach notes and receipts to transactions is a neat touch for those who like to keep everything organized.
Security and Connectivity
In today's digital age, security is paramount. Simplifi uses bank-level security to protect your data, which gives me peace of mind. It's comforting to know that while I'm getting my finances in order, my information is kept safe.
The app also integrates seamlessly with most major banks and financial institutions, ensuring that your data is always up-to-date. No more manual updates, which is a huge time saver!
My Final Thoughts
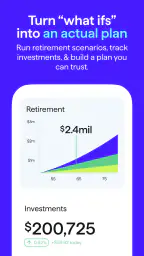
Overall, Quicken Simplifi: Budget Smart is a solid choice for anyone looking to get a grip on their finances. It's packed with features that make budgeting and financial tracking a lot less daunting. Whether you're a seasoned financial guru or just starting to take control of your money, Simplifi is worth checking out.
If you're ready to take the plunge and make your financial life a whole lot easier, you can find the download links right here on our site. Why not give it a try? Your wallet might just thank you.
Where it fits among budgeting options
Compared with a basic spreadsheet, the main appeal here is having account activity, spending patterns, and bill reminders gathered into a more continuous view. A spreadsheet can be better if you want to design every formula yourself, keep records entirely manual, or model an unusual household arrangement in detail. Simplifi is more attractive when you want the app to do much of the routine organizing and are comfortable reviewing connected information rather than entering everything by hand.
It also serves a different purpose from a simple expense-splitting tool. Those are handy when the immediate question is who owes whom after a meal or trip; this app is more relevant to the bigger rhythm of income, bills, subscriptions, and spending. For a shared household, I would not expect it to settle reimbursements or replace an agreed method for splitting costs. I would use it to notice patterns and make better decisions, then handle the actual agreement directly.
Small-business tools and sensible expectations
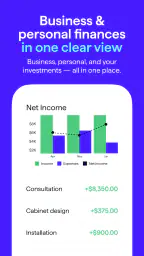
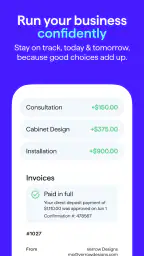
The app now includes tools for small business as well as personal finance, which may appeal to someone who wants to keep an eye on household money and business activity in one budgeting environment. I would still be careful about treating a personal finance app as a complete substitute for dedicated bookkeeping or tax preparation. If your work involves complicated records, reporting obligations, or a need for formal accounting workflows, a purpose-built business system may be the better fit.
For a very small operation, the practical question is whether the available tools suit the way you separate business and personal spending. I would establish that boundary before connecting accounts and avoid assuming that convenience alone makes mixed records easy to interpret. Keeping categories and account choices intentional is more useful than trying to make one dashboard represent every financial detail.
A routine that keeps the app useful
One realistic way to use it is to check the plan before a weekly grocery run, then revisit the transactions afterward and see whether the household’s estimate was realistic. If a bill is coming up, the reminder can prompt a conversation about timing rather than leave one person to discover the pressure at the last minute. Over several check-ins, the reports can help distinguish a one-off expensive week from a recurring pattern that deserves a budget change.
I would avoid making decisions from a single unusually busy day. A useful review asks whether spending is moving in a way that matters over time, and whether the plan still reflects the household’s priorities. Notes on an exceptional purchase can help explain a temporary spike, while custom categories can keep that event from distorting a broader view. The app becomes more valuable when its records lead to a decision, not simply when every screen looks complete.
My household verdict
For a household that wants a shared point of reference without pretending that everyone must merge their finances, Simplifi can make budgeting conversations more grounded. Its spending plan, bill reminders, subscription tracking, reports, and adaptable categories give me useful ways to see what is happening and decide what deserves attention. I would start with a clear purpose, connect only the accounts that fit that purpose, and agree on how the information will be used.
I would skip it if you need a strict manual ledger, a dedicated expense-splitting service, or a comprehensive accounting setup for a complex business. I would also choose another approach if linking financial accounts is a deal-breaker. But if you want a more organized view of personal spending—and possibly a practical starting point for household coordination—this is a thoughtful option. Its best result is not a perfect budget; it is fewer surprises and more useful conversations about where the money needs to go.
Frequently Asked Questions
What features does Quicken Simplifi offer for budget management?
Quicken Simplifi provides a comprehensive suite of features for effective budget management. Users can track expenses, set savings goals, and receive insights on spending patterns. The app also offers personalized financial advice, bill tracking, and real-time updates on account balances, making it a robust tool for personal finance management.
Is Quicken Simplifi secure for linking bank accounts?
Yes, Quicken Simplifi ensures high-level security for linking bank accounts. It uses bank-level encryption and multi-factor authentication to protect user data. The app has a strong reputation for maintaining privacy and security, making users feel confident about connecting their financial accounts.
Can Quicken Simplifi be used across multiple devices?
Quicken Simplifi is designed for multi-device use. It is available on both Android and iOS platforms, allowing seamless synchronization across smartphones and tablets. This ensures users can access their financial data anytime, anywhere, without losing track of their budgeting activities.
Does Quicken Simplifi offer customer support if I encounter issues?
Yes, Quicken Simplifi provides excellent customer support to assist users with any issues. Support options include in-app tutorials, a detailed FAQ section, and direct customer service via email or chat. This ensures users can quickly resolve problems and continue managing their finances effectively.
Is there a cost associated with using Quicken Simplifi?
Quicken Simplifi offers a subscription-based model. While there might be a free trial available for new users, ongoing access requires a monthly or annual fee. This subscription includes all features and regular updates, ensuring users receive the latest tools for managing their finances efficiently.


